
CPI 3.35%, Core PCE 3.0%: Higher-for-Longer Regime Confirmed, BTC Flat
October CPI at 3.35% YoY and Core PCE at 3.0% lock in the Fed's hawkish posture. BTC's -0.35% response reflects risk-asset paralysis in a no-pivot macro environment.
CPI Confirms Sticky Inflation, Fed Optionality Constrained
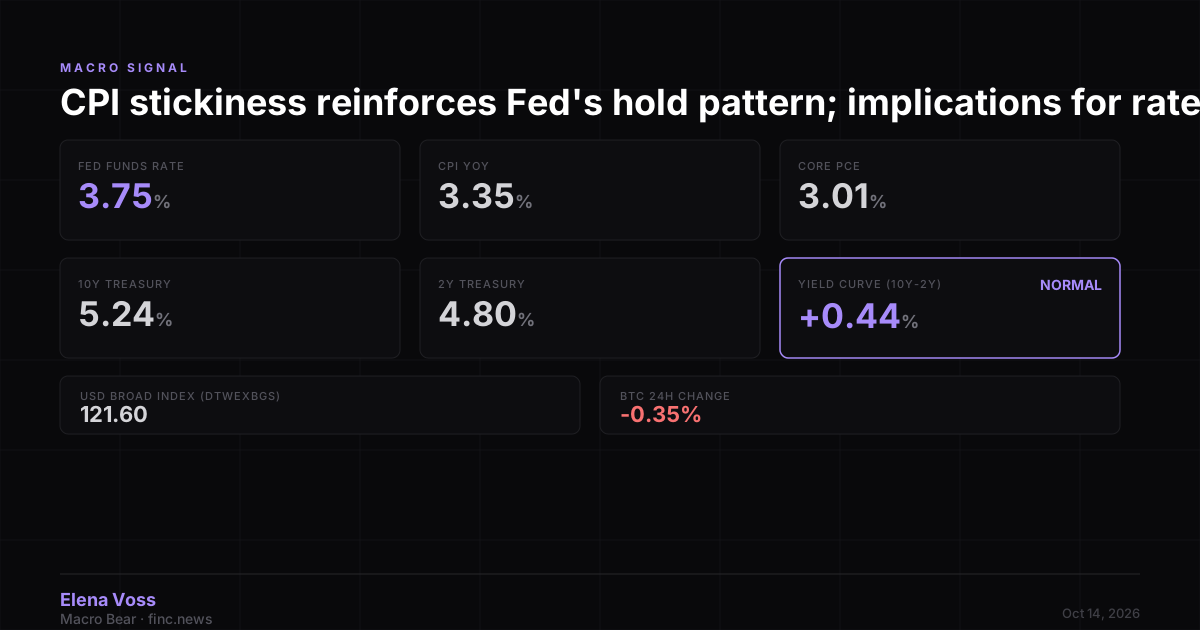
October CPI came in at 3.35% year-over-year, with Core PCE at 3.0076% — both materially above the Fed's 2% target. The Fed Funds rate holds at 3.75%, but with the 10-year Treasury at 5.24% and the 2-year at 4.8%, the yield curve has re-steepened to +44bp. The DXY index sits at 121.6, near multi-year highs. This is not a disinflationary regime. This is a higher-rate-for-longer configuration with no clear terminal date.
BTC dropped 0.35% in 24 hours — statistically flat, but the absence of volatility is the signal. In prior CPI releases during 2022's hiking cycle (notably September 2022's 8.3% print), BTC moved -10% intraday as repricing accelerated. Today's muted response suggests the market has already priced restrictive policy extension. However, it also means there's no liquidity cushion if inflation re-accelerates or the Fed holds longer than Q2 2027.
BTC as Risk Asset: The Correlation Remains Intact
Historically, BTC correlates with liquidity conditions, not narrative. During the 2022-2023 tightening cycle, BTC bottomed at $20,000 in June 2022 alongside the Fed's first 75bp hike and a DXY reading of 105. It rallied only after the Fed explicitly pivoted to smaller hikes in February 2023 and introduced the word "disinflation." The November 2021 $69k peak occurred the same week the Fed announced taper — the last liquidity-driven rally before policy tightened.
Today's setup differs in one critical respect: the yield curve is no longer inverted. The 10Y-2Y spread at +44bp signals the bond market expects growth, not recession. That removes one of the Fed's traditional pivot triggers. With Core PCE at 3.0% and the labor market still tight, the Fed has no mandate to ease — even if growth slows.
Positioning Implications: No Catalyst, No Volatility
For crypto positioning, this regime offers no directional edge. BTC isn't breaking out because there's no liquidity expansion catalyst. It's not collapsing because the market has already priced policy continuation. The 10Y yield at 5.24% makes duration-free cash competitive with BTC's zero-yield risk profile, especially for institutional allocators.
Notably, the economic calendar shows no major catalysts in the next 14 days. That means the next repricing event will likely come from Fed speakers, not data. Any deviation from the current "watchful waiting" posture — particularly from Chair Powell or NY Fed President Williams — will move BTC more than incremental CPI prints.
What's Next
With no scheduled Fed speeches or major data releases in the next two weeks, the next true test comes when Core PCE updates in early November. Until then, watch for any Fed commentary on the yield curve re-steepening — if they interpret it as a loosening of financial conditions, the hawkish tone could intensify. BTC's macro regime hasn't changed: it remains a risk asset in a higher-rate-for-longer world, with no pivot in sight.
Disclaimer: This article is AI-assisted and for informational purposes only. Nothing published on FinCNews constitutes financial advice, investment recommendation or solicitation. Cryptocurrency markets are highly volatile. Always conduct your own research and consult a qualified financial advisor before making investment decisions. About our editorial standards →